
Behavioral Credit Scoring Engine for Instant, Explainable Lending
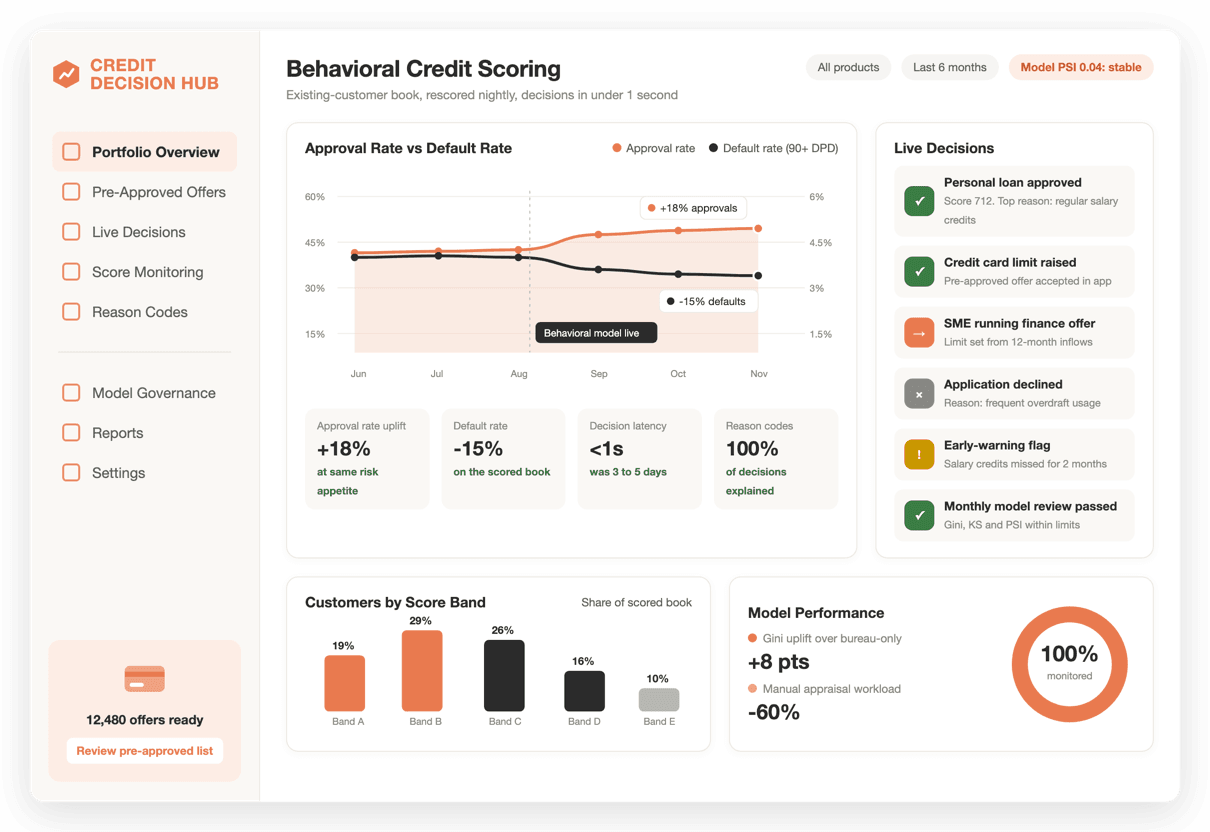
Most existing customers have no bureau-grade credit history, so lending still runs on salary slips and manual appraisal. Stixor's engine turns the bank's own account data into explainable scores and pre-approved offers, delivered in under a second inside the bank's perimeter.
<1s
Decision Latency
100%
Decisions with Reason Codes
+18%
Approval Rate Uplift at Same Risk Appetite
15%
Default Rate Reduction on the Scored Book
Business Overview and Strategic Direction
EXECUTIVE SUMMARY
Banks hold the strongest predictor of repayment they have: how each customer uses their account. Yet consumer and SME lending still depends on salary slips, manual appraisal and conservative limits, because most existing customers have no bureau-grade credit history. Good customers are declined or under-served, turnaround takes days, and transaction data sits unused in core banking.
Stixor built a behavioral scoring engine that scores every existing customer from their own account behavior, pre-approves limits for personal loans, cards and SME working capital, and returns each decision in under a second with reason codes. It runs on the bank's data inside the bank's own environment, and every score is explainable, monitored and documented under model governance.
Operational Challenges
Lending to existing customers should be the bank's easiest growth channel, but the data and process were not set up for it. Key challenges:
PROBLEM STATEMENT
Thin-File Customers
Most existing customers have no bureau-grade credit history, so salaried and self-employed customers are declined or given low limits despite years of healthy account activity.
Slow, Paper-Based Appraisal
Lending relies on salary slips, manual review and branch visits, so a simple personal loan or card decision takes days instead of seconds.
Unused Behavioral Data
Transaction, salary-credit, balance and channel data that best predicts repayment sits in core banking and is not used in credit decisions.
Regulatory and Explainability Demands
Any automated decision must be explainable to customers and auditors, monitored for drift and documented under the bank's model risk governance.
Behavioral Scoring Platform for Pre-Approved Lending
An end-to-end scoring platform that turns account behavior into explainable credit decisions and pre-approved offers across app, branch and SME channels.
Our Solution
Behavioral Risk Modeling
Gradient-boosted models and points-based scorecards trained on transaction, salary-credit, balance and channel behavior estimate each customer's probability of default (PD), including thin-file and salaried customers.
Instant Decisioning and Offers
A real-time decisioning API returns a score, a risk-based limit and the top reason codes in under a second, feeding pre-approved offers for personal loans, credit cards and SME working capital in the app and branch.
Governance and Monitoring
Every score carries reason codes, and models are tracked on Gini, KS and population stability index (PSI), with validation reports, model documentation and audit trails that support model risk management (MRM) and regulator review.
01
Behavioral Feature Engineering
- Salary-credit regularity, average and minimum balances, inflow-outflow ratios and channel usage built from core banking data
- Early-warning signals of financial stress, such as falling balances or missed salary credits, that bureau data often misses
- Separate segment models for salaried, self-employed and SME customers
02
Decisioning and Limit Setting
- Risk-based limits and score cut-offs calibrated to the bank's risk appetite
- Pre-approved offers pushed to the mobile app, internet banking and branch staff
- Champion-challenger testing before any credit policy change goes live
03
Explainability and Compliance
- Reason codes on every approval, decline and limit, ready for customer and auditor queries
- Independent validation, model documentation and full audit logs
- Fairness and stability checks across customer segments, plus behavioral scores for early-warning and IFRS 9 staging
04
Secure Deployment and MLOps
- Runs inside the bank's own perimeter on its own data
- Automated retraining, drift alerts and performance dashboards
- Integrates with core banking, loan origination and card systems through APIs
Business Outcomes
IMPACT & RESULTS
Compact Performance Metrics
<1s
Decision Latency
100%
Decisions with Reason Codes
+18%
Approval Rate Uplift at Same Risk Appetite
15%
Default Rate Reduction on the Scored Book
Operational Efficiency
Days to <1s
Credit Decision Turnaround
60%
Manual Appraisal Workload Reduction
+8 pts
Gini Uplift over Bureau-Only Scores
100%
Models Monitored for Drift and Stability
Technology Stack
TOOLS USED

Python / PyTorch
Scikit-learn

PostgreSQL

Apache Kafka

Docker / K8s

Prometheus


Discuss Your Enterprise Use Case
From small to large scale enterprises, we deliver next-gen AI, data engineering, and actionable insights.


